Running a business in the UAE involves more than maintaining a valid trade licence. Business owners must also manage tax registrations, VAT returns, corporate tax filings, employee visas, work permits, beneficial ownership information, financial records and other regulatory obligations.
With multiple government authorities, free zone regulators and renewal dates involved, keeping everything organised can become challenging — particularly when a business operates multiple entities or employs people from different countries.
In 2026, UAE businesses also need to prepare for the phased introduction of mandatory electronic invoicing, making financial record management and accounting processes increasingly important.
Whether you operate a mainland LLC in Dubai, a free zone company in Abu Dhabi, or a group of businesses across different UAE jurisdictions, having a structured compliance process can help you avoid unnecessary delays, penalties and administrative problems.
This guide provides a practical UAE business compliance checklist for 2026, covering the major obligations businesses should review throughout the year, the documents they should maintain and the deadlines they need to monitor.
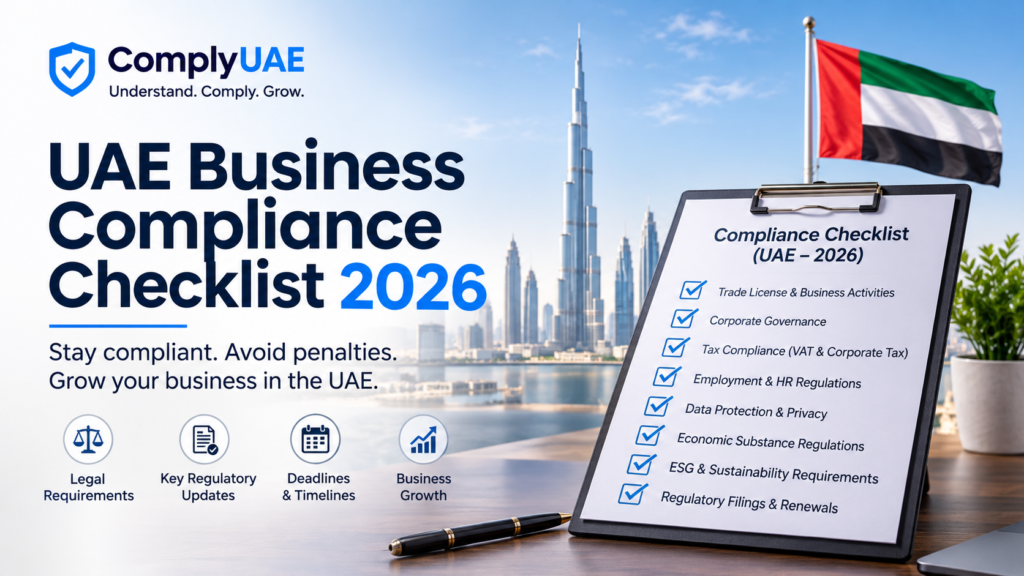
Quick UAE Business Compliance Checklist for 2026
Use this checklist as a starting point to review your company’s compliance position.
| Compliance area | What your business should check |
|---|---|
| Trade licence | Validity, renewal requirements and approved activities |
| Corporate tax | Registration, accounting records, annual return and payment |
| VAT | Registration threshold, VAT returns, payments and records |
| E-invoicing | Implementation timeline and accounting system readiness |
| Beneficial ownership | Updated shareholder and UBO information |
| Employee visas | Residency permits, Emirates ID and visa renewals |
| Work permits | Valid MoHRE or relevant free zone permits |
| Payroll | Salary payments and WPS compliance, where applicable |
| Health insurance | Valid employee health insurance coverage |
| Accounting | Financial statements, invoices and supporting documents |
| Audit | Annual audit requirements under applicable regulations |
| Bank accounts | Valid company documents and updated KYC information |
| AML compliance | Applicable AML/CFT registration, screening and reporting |
| Data protection | Secure handling of customer and employee information |
| Regulatory filings | Any industry-specific or free zone reporting obligations |
Important: Not every requirement applies to every UAE company. Your obligations depend on your legal structure, business activity, annual revenue, tax status, licensing authority and location.
1. Trade Licence Renewal and Business Activity Compliance
A valid trade licence is one of the most important requirements for operating a business in the UAE.
Whether your company is registered with a mainland economic department or a free zone authority, you must ensure that its licence remains valid and that its registered business activities accurately reflect the services or products you offer.
An expired licence can create operational difficulties and may affect other processes, including employee work permit renewals, banking arrangements and government transactions.
Trade licence compliance checklist
- Check the expiry date of your company’s trade licence.
- Confirm that all registered business activities are still accurate.
- Review whether additional approvals are required for your business activities.
- Check the validity of your tenancy contract or registered business premises documentation, where applicable.
- Obtain shareholder or management approvals required for renewal.
- Update the company details if there have been changes in ownership, management or business activities.
- Submit the renewal application through the relevant licensing authority.
- Pay the applicable renewal fees and retain the renewed licence.
Documents commonly required for trade licence renewal
Depending on the licensing authority and company structure, you may need:
- Existing trade licence.
- Tenancy contract or registered office documentation.
- Memorandum of Association (MOA), where applicable.
- Shareholder and authorised signatory documents.
- External government approvals, if required.
- Other documents requested by the relevant authority.
Mainland vs free zone licence renewal
Mainland companies generally deal with the relevant emirate’s Department of Economy and Tourism or economic development authority.
Free zone companies must follow the renewal procedures of their respective free zone authorities.
For example, companies registered in DMCC, DIFC, JAFZA, IFZA and other free zones may have different documentation, audit and renewal requirements.
Practical tip: Do not wait until the final week to initiate a licence renewal. Start reviewing the required documents and approvals well in advance of the expiry date.
2. UAE Corporate Tax Registration, Filing and Payment
Corporate tax is one of the most important compliance areas for UAE businesses in 2026.
The UAE introduced its federal corporate tax regime for financial years beginning on or after 1 June 2023. Businesses must assess whether they fall within the scope of corporate tax, complete the applicable registration process and meet their filing and payment obligations.
UAE corporate tax rates
The standard UAE corporate tax rates are:
| Taxable income | Corporate tax rate |
|---|---|
| Up to AED 375,000 | 0% |
| Above AED 375,000 | 9% |
Qualifying Free Zone Persons may benefit from a 0% rate on qualifying income, subject to meeting the relevant statutory conditions. Non-qualifying taxable income may be subject to the 9% rate.
It is important to understand that having a free zone licence does not automatically mean that all company income is exempt from corporate tax.
Corporate tax compliance checklist
- Determine whether your company is subject to UAE corporate tax.
- Complete corporate tax registration with the Federal Tax Authority (FTA), where required.
- Obtain and maintain your Corporate Tax Registration Number.
- Identify the company’s financial year and applicable tax period.
- Maintain accurate accounting records.
- Reconcile revenue, expenses, assets and liabilities.
- Review related-party transactions and transfer pricing requirements, where applicable.
- Assess eligibility for any applicable tax relief or exemption.
- Prepare and submit the corporate tax return within the statutory deadline.
- Pay any corporate tax due within the applicable deadline.
When is the corporate tax return due?
The general rule is that a taxable person must submit its corporate tax return and pay the tax due within nine months from the end of the relevant tax period.
For example:
| Financial year ending | Corporate tax return and payment deadline |
|---|---|
| 31 December 2025 | 30 September 2026 |
| 31 March 2026 | 31 December 2026 |
| 30 June 2026 | 31 March 2027 |
| 30 September 2026 | 30 June 2027 |
| 31 December 2026 | 30 September 2027 |
These examples assume the relevant financial year is also the company’s corporate tax period.
Small Business Relief in 2026
Eligible UAE resident taxable persons may elect for Small Business Relief if their revenue does not exceed AED 3 million in the relevant tax period and all previous tax periods, subject to the applicable conditions.
An important 2026 development is that the UAE Ministry of Finance extended the availability of Small Business Relief to tax periods ending on or before 31 December 2029.
However, Small Business Relief is not automatic. An eligible business must make the required election in its corporate tax return.
Qualifying Free Zone Persons and members of certain multinational groups are excluded from this relief.
Even businesses claiming Small Business Relief must comply with applicable registration, filing and record-keeping requirements.
Corporate tax documents to maintain
Keep the following documents organised:
- Financial statements.
- Sales and purchase invoices.
- Bank statements.
- Expense records.
- Asset registers.
- Liability records.
- Payroll records.
- Shareholder and ownership information.
- Related-party transaction documentation, where applicable.
- Previous corporate tax returns and supporting calculations.
The FTA generally requires relevant corporate tax records to be retained for at least seven years following the end of the relevant tax period.
Practical tip: Do not treat corporate tax compliance as an annual activity that begins just before filing. Accurate bookkeeping and supporting documentation should be maintained throughout the financial year.
3. VAT Registration, Returns and Payments
Value Added Tax (VAT) is another important compliance requirement for UAE businesses.
The standard VAT rate in the UAE is 5%. Businesses making taxable supplies must monitor their turnover to determine whether they need to register with the Federal Tax Authority.
UAE VAT registration thresholds
| Registration type | Threshold |
|---|---|
| Mandatory VAT registration | AED 375,000 |
| Voluntary VAT registration | AED 187,500 |
Mandatory registration generally applies when the value of taxable supplies and imports exceeds AED 375,000 over the previous 12 months or is expected to exceed that amount within the next 30 days.
Businesses may voluntarily register if their taxable supplies, imports or eligible taxable expenses exceed AED 187,500 under the applicable rules.
The threshold does not apply in the same way to foreign businesses making taxable supplies in the UAE.
VAT compliance checklist
- Review your annual and rolling 12-month taxable turnover.
- Register for VAT when the mandatory threshold is met.
- Obtain your Tax Registration Number (TRN).
- Display the TRN on applicable tax invoices.
- Issue tax invoices that meet UAE VAT requirements.
- Record VAT collected on sales.
- Record eligible input VAT on business purchases.
- Reconcile VAT records with accounting entries.
- Review zero-rated, exempt and standard-rated transactions.
- Submit VAT returns within the prescribed deadlines.
- Pay the VAT due to the FTA.
When should VAT returns be filed?
VAT returns and related payments are generally due within 28 days from the end of the relevant tax period.
The applicable tax period may be monthly or quarterly, depending on the FTA’s assignment.
For example, if your VAT tax period ends on 31 March, the return and payment will generally be due by 28 April.
Missing a VAT filing deadline can result in administrative penalties.
VAT records to maintain
Businesses should maintain:
- Sales invoices.
- Purchase invoices.
- Credit notes and debit notes.
- Import and export documentation.
- Customs declarations, where applicable.
- VAT calculations.
- Bank statements.
- VAT returns and payment confirmations.
VAT invoices must generally be retained for at least five years, subject to applicable extended retention requirements for certain records and circumstances.
Practical tip: Reconcile your VAT figures with your accounting records before submitting the return. Differences between reported sales, purchases, bank transactions and VAT calculations can create problems during an FTA review.
4. UAE E-Invoicing Compliance: Prepare for the 2027 Rollout
One of the most important developments businesses should prepare for in 2026 is the UAE’s electronic invoicing programme.
The system is designed to enable structured electronic invoice exchange between businesses and reporting to the Federal Tax Authority.
An important distinction is that sending a PDF invoice by email does not, by itself, constitute an electronic invoice under the UAE e-invoicing framework.
Who needs to prepare?
The framework covers business-to-business (B2B) and business-to-government (B2G) transactions, including businesses that are not VAT registered, subject to the applicable rules.
E-invoicing implementation timeline
The announced implementation schedule includes:
| Business category | Appoint an Accredited Service Provider by | Implementation date |
|---|---|---|
| Businesses with revenue of AED 50 million or more | 31 July 2026 | 1 January 2027 |
| Businesses with revenue below AED 50 million | 31 March 2027 | 1 July 2027 |
| Government entities | 31 March 2027 | 1 October 2027 |
The programme also includes a pilot phase beginning in July 2026.
Businesses should verify their applicable implementation category and any subsequent amendments to the programme before relying on these dates.
E-invoicing preparation checklist
- Review your existing invoicing process.
- Identify the accounting or ERP software currently being used.
- Understand the structured invoice requirements.
- Assess whether your existing system can integrate with an Accredited Service Provider.
- Review your customer and supplier data.
- Identify the person responsible for e-invoicing implementation.
- Review the implementation timeline applicable to your revenue category.
- Plan the necessary technology and accounting process changes.
Why prepare in 2026?
Businesses that begin preparing early can identify gaps in their accounting systems, invoice formats and transaction records before mandatory implementation begins.
5. Ultimate Beneficial Ownership (UBO) and Shareholder Records
UAE businesses must maintain accurate information about their ownership structures and ultimate beneficial owners, subject to applicable exemptions and regulatory requirements.
An Ultimate Beneficial Owner is generally an individual who ultimately owns or cont